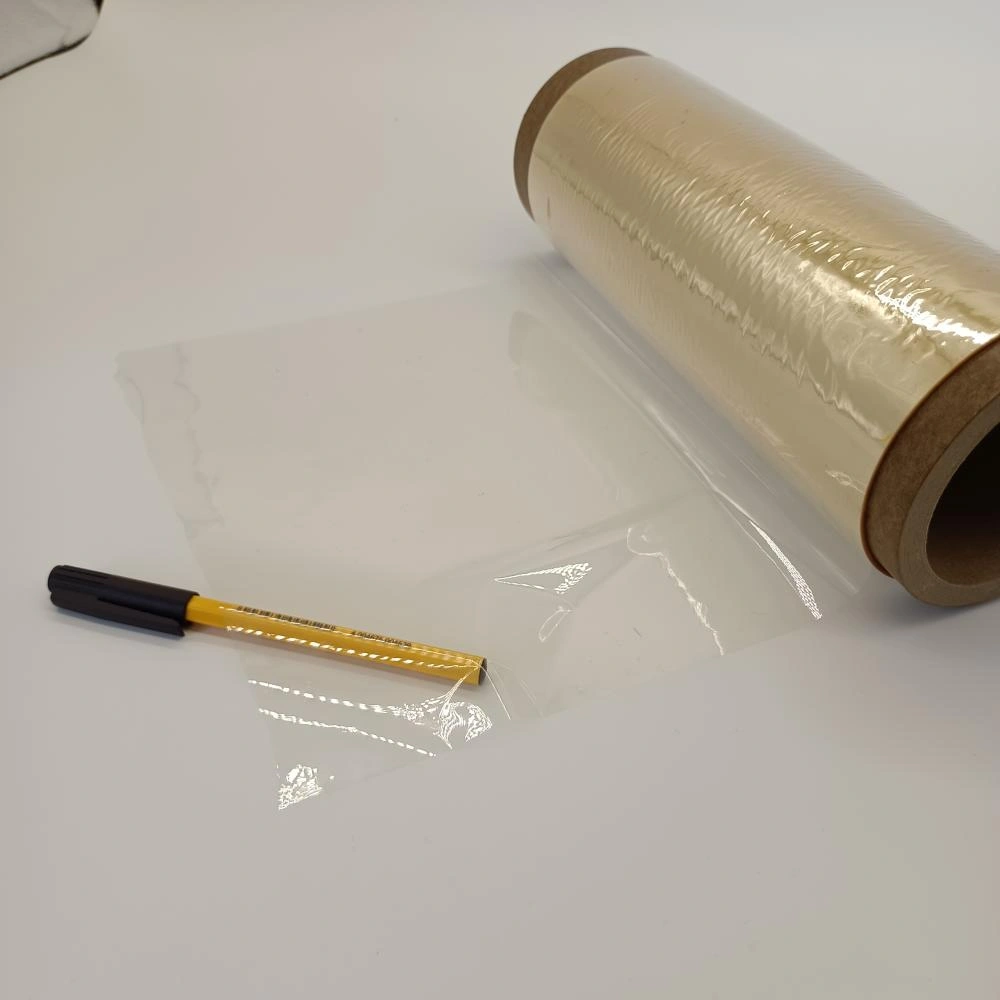
The demand for CPI films stems from their unique ability to combine electrical insulation and mechanical durability with high optical transparency. As manufacturers prioritize thinner, more resilient components for compact devices, these films have become a critical alternative to traditional cover glass. The electronics sector remains the primary consumer, fueled by the push toward miniaturization and the development of 5G and 6G components.
Material innovation is also a key driver, with the fluorinated polyimide segment expected to lead growth through 2031. The incorporation of fluorine atoms into film formulations improves optical clarity and reduces dielectric constants, making them ideal for the next generation of foldable smartphones and optoelectronic devices. Regionally, Asia Pacific dominates the landscape, anchored by an established ecosystem of display producers and specialty material manufacturers. While investment funding in the sector saw a volatile period between 2020 and 2022, a significant rebound in 2024—reaching over $700 million—signals renewed confidence in the commercial viability of these high-performance polymers.


Comments (0)
No comments yet. Be the first!